Is Vanguard’s Robo-Advisor Worth It?
Vanguard built its reputation on low-cost index investing, and Vanguard Digital Advisor is the automated version of that same philosophy: four broad index ETFs, a net fee of roughly 0.15% a year, and a $100 minimum. It’s one of the cheapest robo-advisors available from a major brokerage — but “cheap” isn’t the same as “right for everyone.” Here’s a full breakdown of what you actually get.
Quick Verdict
Vanguard Digital Advisor is a strong fit for a hands-off investor who wants a simple, low-cost, buy-and-hold portfolio — particularly inside an IRA, where its lack of tax-loss harvesting doesn’t matter. It’s a weaker fit for anyone who wants portfolio customization, human advisor access at this tier, or tax-loss harvesting on a large taxable account.
Rating snapshot: Low cost ✓✓✓✓✓ | Simplicity ✓✓✓✓✓ | Customization ✓✓ | Tax tools ✗ | Human advice at this tier ✗
The Basics
| Vanguard Digital Advisor | |
|---|---|
| Advisory fee | ~0.15% net annually (gross ~0.20%, credited down) |
| Account minimum | $100 (as low as $5 for some eligible 401(k) accounts) |
| Underlying funds | 4 Vanguard ETFs: VTI, VXUS, BND, BNDX |
| Tax-loss harvesting | Not offered |
| Human advisor access | Not at this tier — available via Vanguard Personal Advisor Services (0.30%, $50,000 minimum) |
| Rebalancing | Threshold-based — triggers when allocation drifts more than a few percentage points from target |
| Account types | Taxable, Roth IRA, Traditional IRA, and eligible employer plans |
How the Portfolio Is Built
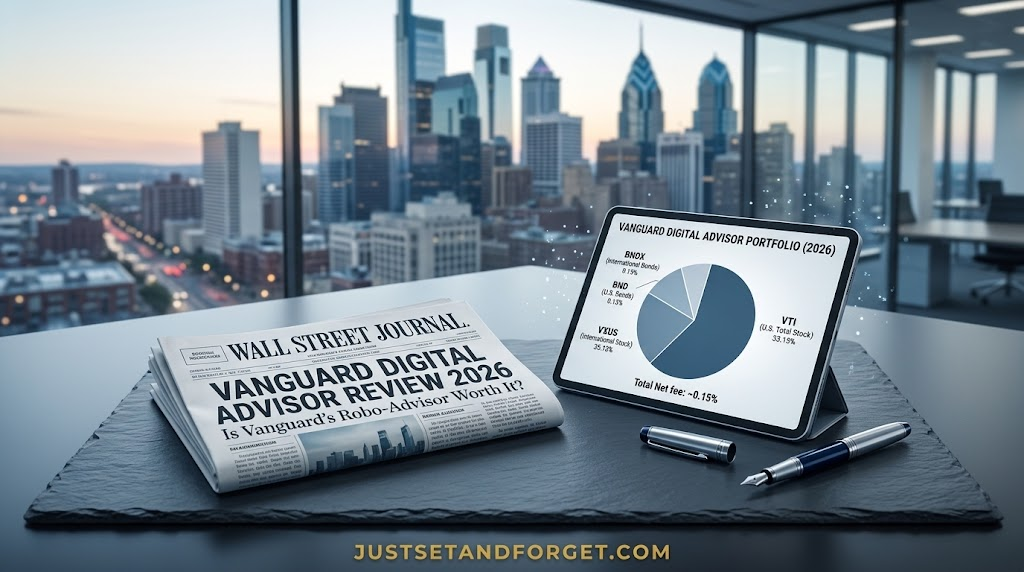
Vanguard Digital Advisor keeps things deliberately simple. Rather than spreading your money across dozens of asset classes, it builds your portfolio from four funds: a total U.S. stock market ETF (VTI), a total international stock ETF (VXUS), a U.S. bond ETF (BND), and an international bond ETF (BNDX).
The allocation between those four shifts based on your risk score and time horizon — a younger investor with decades until retirement might hold mostly equities, while someone closer to retirement holds a larger bond allocation.
This is essentially an automated version of the classic “three-fund portfolio” popular in the passive-investing community, with an added bond diversification layer. Rebalancing is threshold-based rather than constant — the portfolio only trades when your allocation drifts meaningfully from target, which keeps trading (and any associated costs) to a minimum. For a genuinely “set and forget” investor, that simplicity is a feature, not a limitation — though it does mean less flexibility than platforms offering ESG tilts, sector customization, or individual stock exposure.
Fees: Where the Real Cost Sits
Vanguard advertises a gross advisory fee of approximately 0.20%, but investors receive a credit for the expense ratios of the underlying Vanguard funds, bringing the net cost down to roughly 0.15% a year. On a $10,000 account, that works out to about $15 a year — meaningfully less than the 0.25% charged by Betterment, Wealthfront, or SoFi, though not as low as Schwab’s $0 fee or Fidelity Go’s free tier under $25,000.
The tradeoff for that low fee is the mandatory reliance on Vanguard’s own funds — there’s no option to swap in outside ETFs or exclude specific sectors. For an investor who already trusts Vanguard’s index fund philosophy, that’s not really a downside. For someone who wants more control over fund selection, it’s a real constraint.
What’s Missing
Two features that matter to some investors are absent at this tier:
Tax-loss harvesting. Neither Vanguard Digital Advisor nor Vanguard Personal Advisor Services offers automated tax-loss harvesting. For a taxable account where you’re actively trying to offset capital gains, this is a real gap compared to Betterment or Wealthfront. For an IRA, it’s irrelevant either way, since IRA gains aren’t taxed annually.
Human advisor access. Digital Advisor is fully automated — there’s no option to speak with a person at this tier. If you want that, Vanguard’s next tier up, Personal Advisor Services, adds CFP-backed guidance at a 0.30% fee, but requires a $50,000 minimum, a significant jump from Digital Advisor’s $100 entry point.
Who Vanguard Digital Advisor Is Actually Built For
IRA investors who want a simple, low-cost, buy-and-hold portfolio. Since tax-loss harvesting doesn’t apply inside an IRA anyway, Vanguard Digital Advisor’s missing TLH feature costs you nothing in that context — you get Vanguard’s low-cost index philosophy at one of the lowest fees available.
New investors who want a low bar to entry. At $100, the minimum is far more accessible than Schwab’s $5,000, and the fee is lower than most percentage-based competitors.
Investors who already trust Vanguard’s index philosophy and don’t feel the need for portfolio customization beyond risk-score-based allocation.
Less ideal for: large taxable accounts where tax-loss harvesting would provide real value, or investors who want the option of human advisor access without committing $50,000 to Vanguard’s Personal Advisor tier.
How It Compares at a Glance
| Vanguard Digital Advisor | Schwab Intelligent Portfolios | Betterment | |
|---|---|---|---|
| Fee | ~0.15% | $0 (plus cash drag) | 0.25% |
| Minimum | $100 | $5,000 | $0 |
| Tax-loss harvesting | No | Only above $50,000 | Yes |
For the full head-to-head against Schwab, see our Schwab Intelligent Portfolios vs. Vanguard Digital Advisor comparison.
Our Methodology
This review is based on publicly available fee schedules, account minimums, and product disclosures published by Vanguard as of 2026. Fee figures reflect the standard advisory fee before any promotional pricing, which can change without much notice — always confirm current terms directly on Vanguard’s website before opening an account.
We do not maintain an active Vanguard Digital Advisor account for this specific review; treat this article as a starting point for your own research.
Frequently Asked Questions
What’s the actual minimum to open a Vanguard Digital Advisor account? $100 for most investors, though some eligible 401(k) accounts have had minimums as low as $5.
Does Vanguard Digital Advisor offer tax-loss harvesting? No, at either the Digital Advisor or Personal Advisor Services tier.
What’s the difference between Vanguard Digital Advisor and Vanguard Personal Advisor Services? Digital Advisor is fully automated at ~0.15% with a $100 minimum. Personal Advisor Services adds access to a human CFP at 0.30%, but requires a $50,000 minimum.
Can I customize the portfolio beyond the four core funds? Not significantly. Vanguard Digital Advisor’s portfolio is built exclusively from Vanguard’s own ETFs, with allocation adjusted by risk score rather than manual fund selection.
This article is for informational and educational purposes only and does not constitute personalized financial or investment advice. Fees, minimums, and features change frequently — always confirm current terms directly on each provider’s website before opening an account. This post may contain affiliate links; see our affiliate disclosure for details.